Key global InsurTech investment stats in Q1 – Q3 2026:
- Global InsurTech funding grew 57% YoY
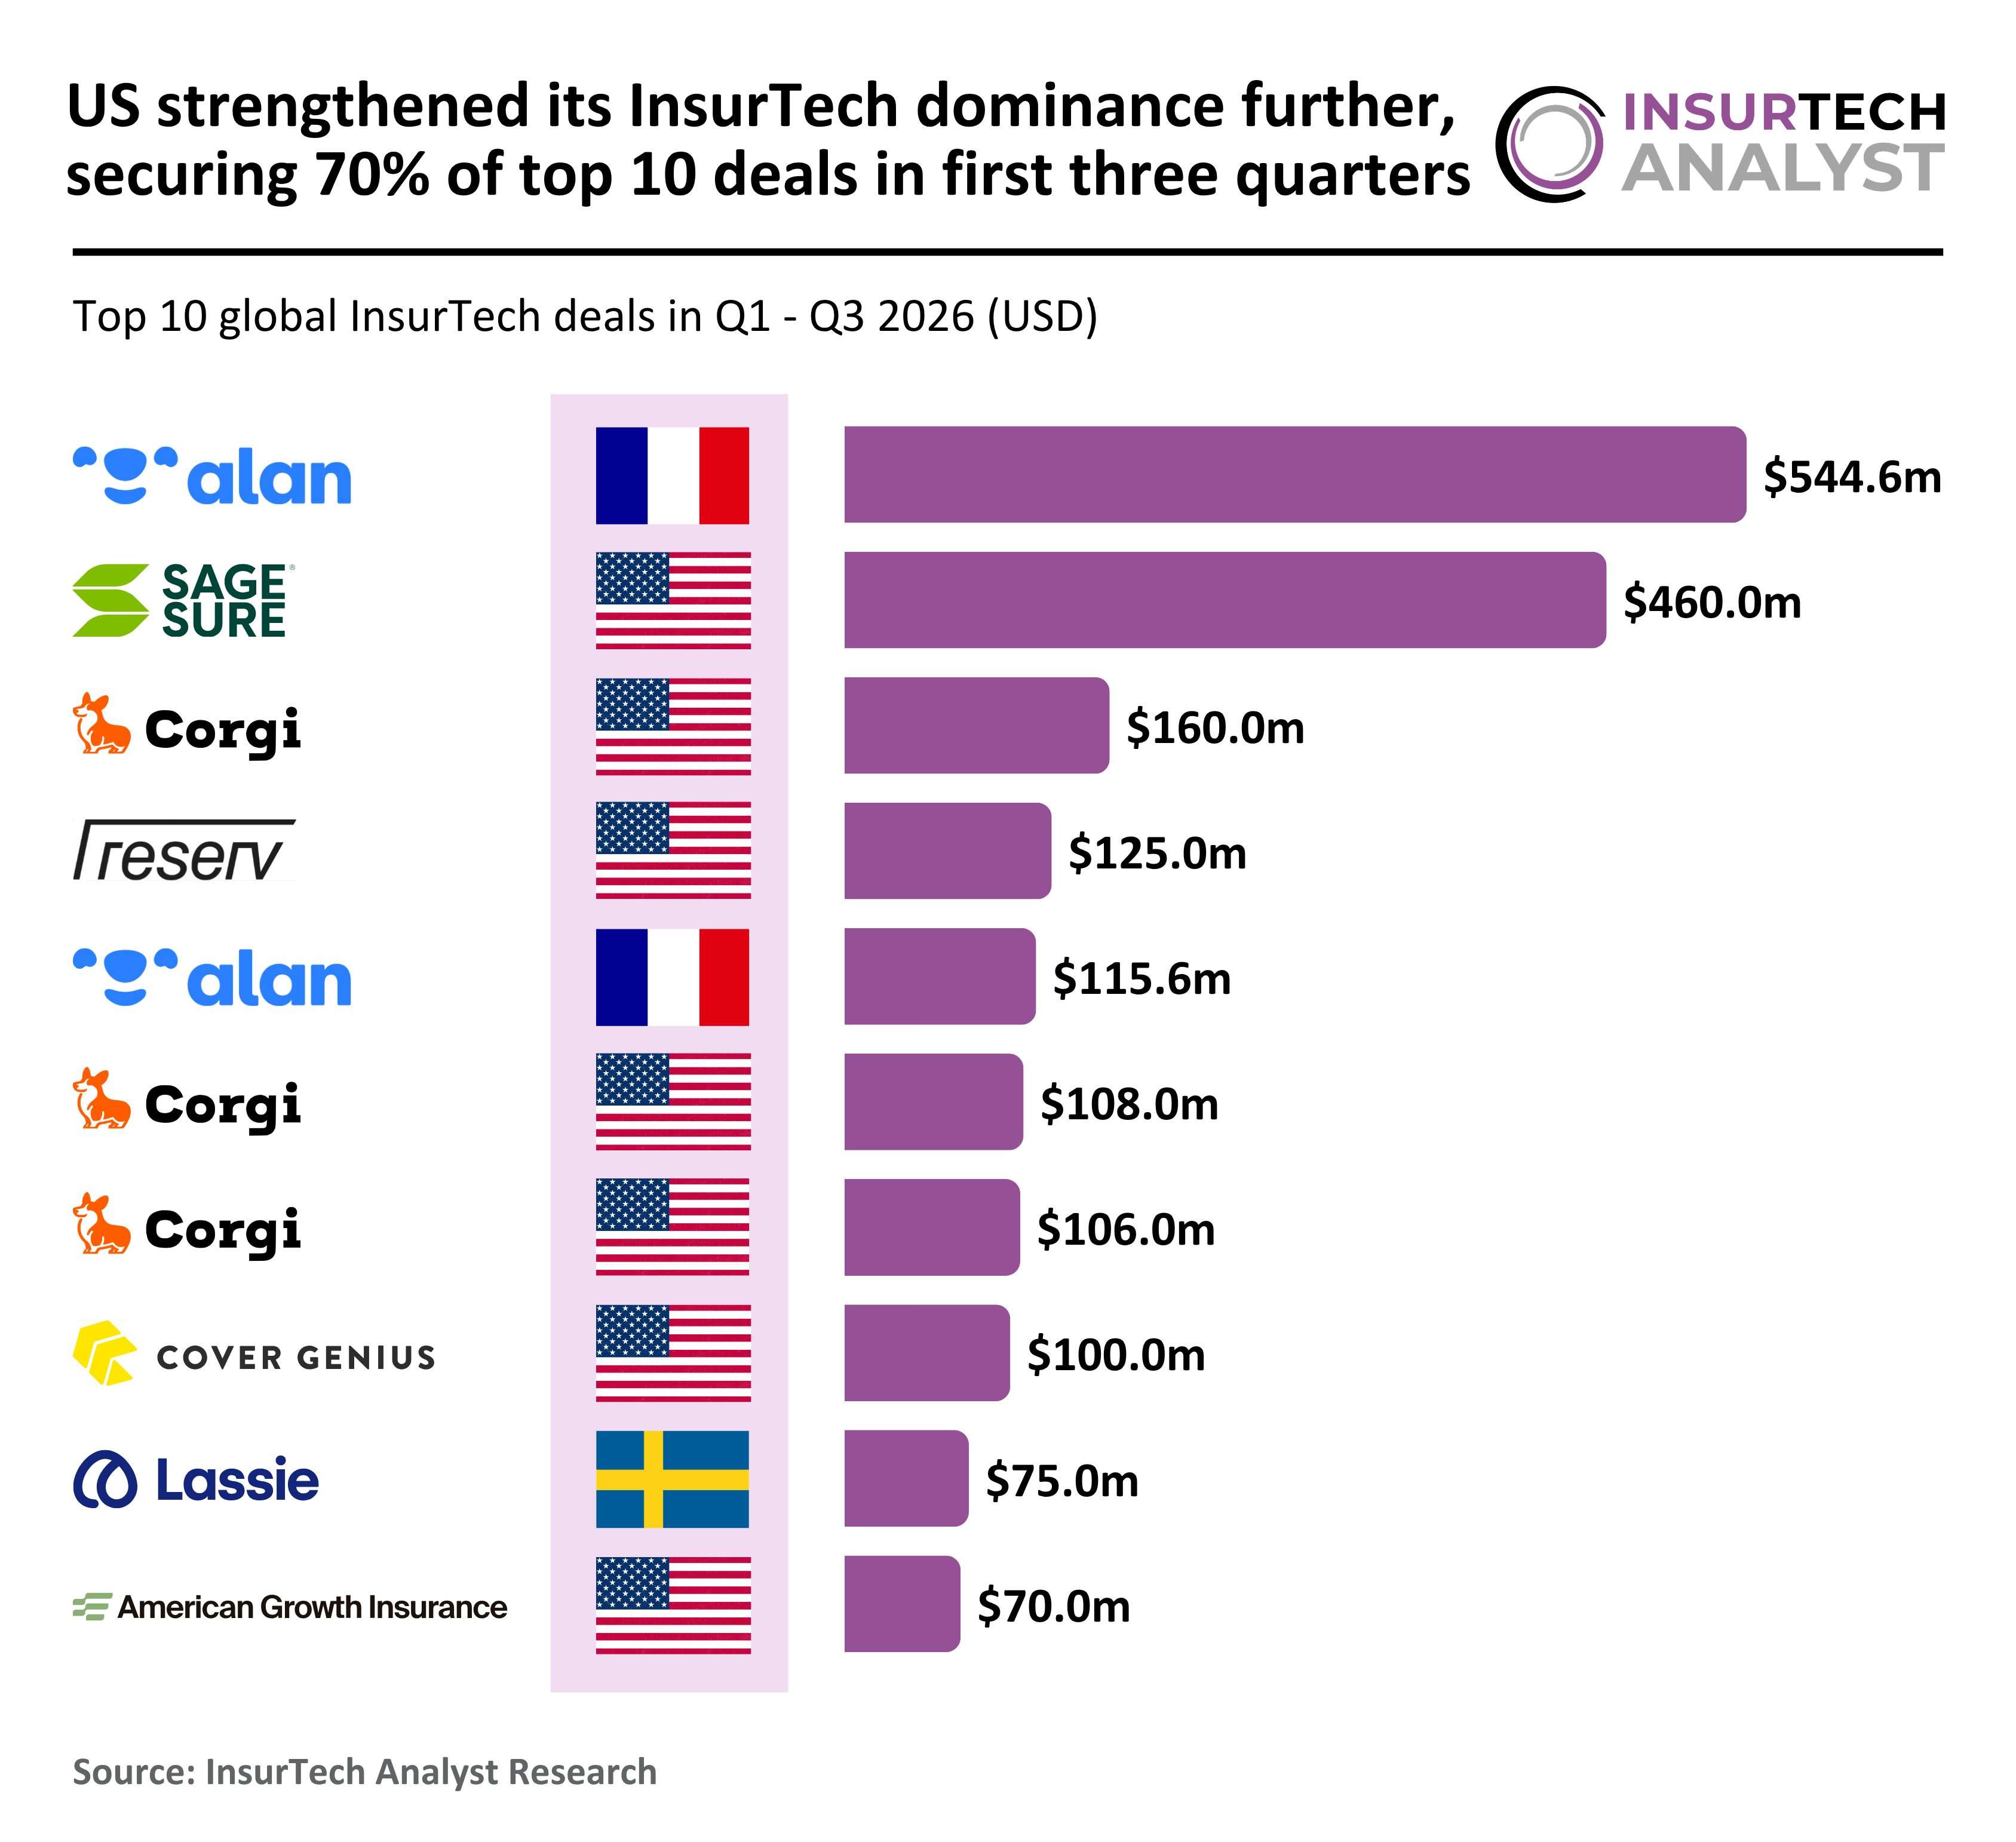
- US companies secured 7 of the top 10 deals to strengthen the country’s dominance in the global InsurTech market
- Alan, a digital health insurance platform serving employees, freelancers and retirees across France, Spain, Belgium and Canada, raised $544.6m making it the top InsurTech deal of the first three quarters
Global InsurTech funding grew 57% YoY
Global InsurTech investment in the first three quarters of 2026 reached $3.5bn across 143 deals, representing a 57% increase in funding compared to the $2.2bn raised across 154 deals in the same period of 2025.
Deal volume fell by 7% year-on-year, meaning the substantial rise in total capital raised was driven by larger individual transactions rather than a broadening of activity.
The average deal value climbed to $24.7m from Q1 to Q3 2026, up from $14.6m over the same period in 2025, a 69% increase that points to investors deploying capital with considerably greater conviction.
The overall picture is one of a sector in which funding momentum is building strongly, even as the total number of transactions contracts.
US companies secured 7 of the top 10 deals to strengthen the country’s dominance in the global InsurTech market
The country-level breakdown of the top 10 deals during the period Q1-Q3 2026 shows the US consolidating its position at the top of the table, accounting for seven of the 10 largest transactions, up from five in the equivalent period of 2025.
France secured two top deals, a new appearance that signals growing scale among its leading InsurTech businesses.
Sweden also made its first appearance with one top deal.
The UK, which had contributed two top deals in Q1 to Q3 2025, was absent from the more recent period, a notable shift given its typically prominent role in the sector.
Germany, Bermuda and South Africa, each of which featured once in Q1 to Q3 2025, similarly did not appear in Q1 to Q3 2026.
The departure of several established markets from the upper end of the rankings, replaced by a tighter set of predominantly US and European entrants, reflects a gradual shift in where the world’s largest InsurTech transactions are being struck.
Alan, a digital health insurance platform serving employees, freelancers and retirees across France, Spain, Belgium and Canada, raised $544.6m making it the top InsurTech deal of the first three quarters
The round was led by Prosus.
Alan now serves more than 1.1 million members and 37,000 businesses.
Much of the company’s durability can be attributed to its distribution strategy, which is built primarily through employer channels and group benefits rather than costly direct-to-consumer acquisition, a model that delivers structurally higher retention and more predictable loss ratios than many of its digital-first peers managed.
Its AI-native platform is described as central to claims automation, care navigation and prevention, and at this scale the operational numbers suggest the model is holding together.
Alan expanded into Spain, Belgium and Canada only after validating its core economics in France, a discipline that set it apart from the wave of InsurTechs that scaled across borders before proving local unit economics and were undone by the regulatory complexity that makes European insurance particularly unforgiving.
Having survived where most challengers did not, Alan now sets a new benchmark for what institutional investors consider an investable InsurTech: disciplined distribution, demonstrable unit economics and a credible path to profitability in at least one market before expansion.
Keep up with all the latest InsurTech news here
Copyright © 2026 InsurTech Analyst